The Satellite Revolution: How Starlink is Redefining the In-Flight Connectivity Experience

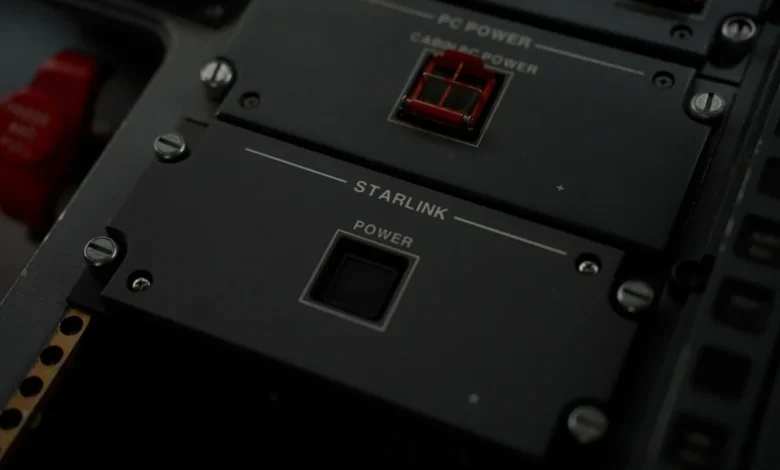
The landscape of commercial aviation connectivity is undergoing a seismic shift as SpaceX’s Starlink emerges as the gold standard for in-flight Wi-Fi. For decades, the passenger experience regarding airborne internet was defined by frustration: high costs, latency-heavy connections, and unreliable uptime. Today, however, the industry is witnessing an aggressive pivot toward low-Earth orbit (LEO) satellite technology, effectively turning high-speed, streaming-capable internet into a fundamental passenger expectation rather than a luxury amenity.
The Evolution of In-Flight Connectivity
To understand the current fervor surrounding Starlink, one must first look at the technological limitations that preceded it. Historically, airlines relied on Air-to-Ground (ATG) systems, which utilize cell towers on the ground to beam signals to aircraft. While functional for basic email and text-based messaging, these systems struggled with bandwidth capacity, often becoming unusable when multiple passengers attempted to stream video or participate in video conferences simultaneously.
The subsequent rise of Ku-band and Ka-band satellite systems offered an improvement, but these relied on geostationary (GEO) satellites positioned 22,000 miles above the Earth. The resulting latency—the time it takes for data to travel from the user to the satellite and back—made real-time interactions difficult. Starlink, by contrast, operates a constellation of thousands of satellites in LEO, situated only about 340 miles above the surface. This proximity drastically reduces latency and increases throughput, allowing for connection speeds that rival high-end residential broadband.
A Chronology of the Connectivity Arms Race
The rapid adoption of Starlink did not happen overnight. The integration began with strategic partnerships aimed at modernizing aging cabin technology.
- 2021: SpaceX begins aggressive testing of its "Aero Terminal," a high-performance antenna designed to withstand the rigors of flight, including extreme temperatures and high-velocity turbulence.
- 2022: JSX, a semi-private regional carrier, becomes the first airline to officially integrate Starlink, signaling to the wider industry that the technology was flight-ready.
- 2023: Major legacy carriers begin formalizing partnerships. Hawaiian Airlines signs a high-profile deal to equip its fleet, followed by announcements from United Airlines, which commits to a comprehensive rollout across its mainline and regional aircraft.
- 2024: The adoption wave intensifies. Air France-KLM, Lufthansa Group, and International Airlines Group (IAG) move to incorporate Starlink, effectively turning the technology into a global competitive mandate.
This chronology reflects a shift from "experimental status" to "industry standard" in less than three years. Airlines that were previously hesitant to invest in expensive retrofits are now rushing to secure contracts to avoid being perceived as technologically obsolete by the business traveler demographic.
The Competitive Landscape: Who Is In and Who Is Out
The adoption of Starlink is not universal, leading to a visible stratification in the aviation market. In the United States, the competitive lines are clearly drawn. United Airlines has emerged as a vocal proponent, positioning the technology as a cornerstone of its "United Next" strategy. Other regional operators, such as JSX, have used Starlink as a primary marketing tool to differentiate their service from larger, slower-moving competitors.
Conversely, some major players have opted to stick with legacy providers or alternative satellite constellations. Delta Air Lines, for instance, has invested heavily in proprietary, high-speed Wi-Fi systems through partnerships with Viasat, aiming to maintain control over the passenger interface and data monetization. JetBlue and Allegiant remain notable holdouts, prioritizing different cabin experience investments or waiting for the long-term reliability metrics of the LEO market to stabilize further.
Internationally, the trend is even more pronounced. The IAG (parent company of British Airways and Iberia), Air France, and Lufthansa Group have recognized that modern long-haul passengers view connectivity as a prerequisite for productivity. In the Middle East, Qatar Airways and Emirates have begun integrating Starlink to ensure their premium cabin experiences remain at the forefront of global luxury, where high-speed internet is now considered as vital as lie-flat seating.
Data-Driven Passenger Demand
The shift is heavily driven by shifting passenger demographics. According to recent industry surveys, nearly 70% of travelers consider in-flight Wi-Fi a top-three factor when booking a flight, ranking it alongside pricing and scheduling. Furthermore, the "streaming generation"—passengers who expect seamless access to Netflix, YouTube, or work-based cloud platforms like Microsoft Teams—have little patience for the "buffered" experience of the past.
Social media sentiment analysis confirms this shift in leverage. Platforms such as X (formerly Twitter) and Reddit have become forums where frequent flyers share "connectivity reports," often shunning airlines that fail to provide stable connections. This public accountability has forced airlines to prioritize connectivity infrastructure as a core component of their brand identity. Some airlines have begun implementing "free Wi-Fi" models, subsidized by loyalty programs or premium ticket tiers, knowing that the Starlink backend is robust enough to handle the surge in traffic without degrading service quality.
Official Responses and Technical Integration
Industry representatives from airlines partnering with SpaceX frequently highlight the "ease of use" factor as the primary driver for adoption. Unlike older systems that required complex sign-in portals, Starlink-equipped aircraft typically allow for a seamless "click-to-connect" experience, which reduces the friction for passengers and decreases the burden on flight attendants to troubleshoot technical issues.
SpaceX, for its part, has maintained a relatively low profile regarding individual airline deals, focusing instead on the scalability of its satellite production and the certification of its Aero Terminals by the Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA). The certification process is rigorous, requiring extensive testing to ensure that the electronically steered phased-array antennas do not interfere with aircraft avionics or ground-based communications.
The Broader Economic and Operational Implications
The implications of this transition extend beyond mere passenger convenience. For airlines, reliable connectivity opens new revenue streams, including:
- Ancillary Revenue: Airlines can offer tiered connectivity packages, such as a free basic tier for messaging and a premium tier for high-definition streaming.
- Data Analytics: Consistent connectivity allows for real-time telemetry from the aircraft to the airline’s operations center, enabling predictive maintenance and improved fuel efficiency.
- Enhanced Crew Efficiency: Flight attendants can access real-time passenger data, dietary requirements, and flight connection updates, leading to more personalized service.
However, the rapid rollout of Starlink also poses challenges. The cost of retrofitting an entire fleet with LEO-capable antennas is substantial, costing millions of dollars per aircraft. For airlines already grappling with thin profit margins, aging fleets, and fluctuating fuel prices, the decision to invest in Starlink is a calculated risk. They must balance the immediate capital expenditure against the long-term threat of losing market share to competitors who offer a superior digital experience.
Analysis: A New Era of Airborne Utility
The transition to LEO-based in-flight connectivity represents the most significant improvement to the passenger experience since the introduction of personal in-seat entertainment systems in the 1990s. While early adopters of Starlink currently enjoy a distinct competitive advantage, the technology is rapidly becoming a commodity.
In the next five years, the industry will likely reach a saturation point where the absence of high-speed, LEO-powered internet will be viewed as a major operational failure. Airlines currently on the sidelines will eventually be forced to choose between massive retrofits or losing their standing with the modern business traveler.
Ultimately, the Starlink revolution is not just about faster internet; it is about the integration of the aircraft into the global digital ecosystem. As the distinction between "being on the ground" and "being in the air" continues to blur, the airline that provides the most reliable connection will likely emerge as the carrier of choice for the increasingly connected global traveler. The "hit-or-miss" era of in-flight Wi-Fi is effectively over, replaced by a new standard of high-performance connectivity that is set to define the next decade of commercial aviation.