Allegiant Air Navigates the Digital Frontier: Balancing Specialized Networks with the Rise of AI-Driven Travel Distribution

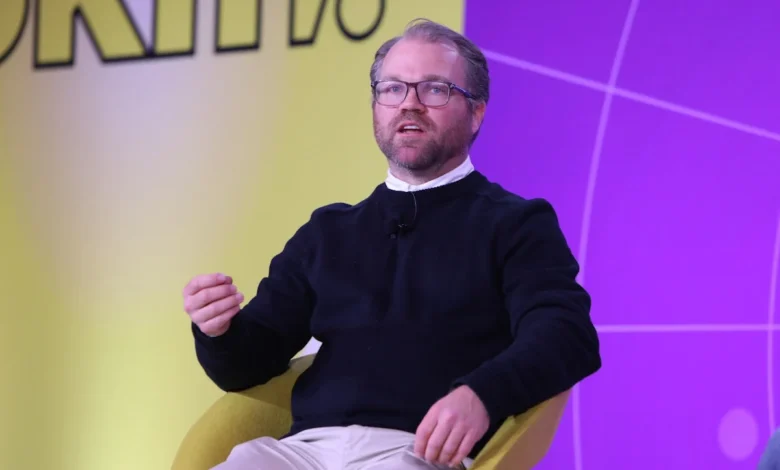
At the Skift Aviation Forum, Drew Wells, the Executive Vice President and Chief Commercial Officer of Allegiant Air, articulated a complex strategic pivot for the ultra-low-cost carrier (ULCC). As the travel industry grapples with the rapid integration of artificial intelligence and shifting consumer search habits, Allegiant finds itself at a critical juncture: how to maintain its highly specific, point-to-point business model while ensuring it remains visible to the modern, tech-savvy traveler who increasingly relies on third-party aggregators and generative AI platforms to plan their itineraries.
The discussion, moderated by Skift Editor-in-Chief Sarah Kopit, highlighted the tension between maintaining direct-to-consumer distribution—a hallmark of cost-efficient airlines—and the necessity of meeting customers where they are in the fragmented digital landscape. For Allegiant, which focuses on underserved secondary markets, this is not merely a technical challenge but a fundamental question of brand identity and operational control.
The Evolution of the Allegiant Distribution Model
Allegiant’s historical success has been built upon a lean operational model. Unlike legacy carriers that rely heavily on global distribution systems (GDS) and complex interline agreements, Allegiant has long prioritized direct bookings through its own website. This strategy allows the airline to avoid high booking fees and maintain total control over the customer experience, from seat selection to the bundling of ancillary services like hotel stays and car rentals.
However, the digital landscape has shifted. According to recent industry data, over 60% of leisure travelers now use online travel agencies (OTAs) or metasearch engines during the inspiration phase of their journey. As travelers lean on AI-powered chatbots and predictive search engines to curate travel experiences, airlines that are absent from these platforms risk being invisible to a growing segment of the market.
Wells confirmed that Allegiant is responding to this by expanding its distribution partnerships, most notably with Expedia. This represents a strategic concession: while the airline prefers direct engagement, the cost of customer acquisition through traditional digital advertising channels has risen significantly. By leveraging the reach of Expedia, Allegiant can access a broader customer base, even if it means ceding some control over the booking interface and paying associated transaction fees.
Chronology of Digital Transformation in Aviation
The airline industry has undergone several distinct phases of distribution, each altering the balance of power between carriers and travel sellers.
- The Pre-Internet Era: Airlines relied on travel agents and GDS providers, paying significant commissions to ensure seat availability.
- The Direct-Booking Revolution (2000–2015): Budget carriers like Allegiant and Ryanair championed the "direct-only" model to bypass GDS fees, which were estimated to cost airlines upwards of $10 to $20 per booking.
- The Rise of Metasearch (2015–2022): Platforms like Google Flights and Kayak forced airlines to compete on price transparency, leading to the proliferation of "Basic Economy" fare classes.
- The AI Disruption (2023–Present): Generative AI has moved from simple price comparison to itinerary curation. AI agents can now synthesize personal preferences, budget constraints, and real-time availability to suggest entire trips, bypassing traditional airline websites entirely.
The AI Dilemma: Caution vs. Opportunity
During the Skift Aviation Forum, Wells emphasized a "cautious approach" toward AI booking agents. While the industry is currently enamored with the efficiency of generative AI, airline executives remain wary of the risks involved. One of the primary concerns is the "black box" nature of AI decision-making. If an AI agent recommends an itinerary, the airline has little visibility into why that specific flight was chosen over a competitor’s.
Furthermore, there is the risk of "brand dilution." When a traveler books through a third-party AI interface, the airline’s ability to upsell ancillary products—which account for a significant portion of Allegiant’s revenue—is severely diminished. Ancillary revenue, including baggage fees, seat assignments, and onboard sales, has become the lifeblood of the ULCC business model. If an AI agent strips away the brand’s ability to present these options clearly, the airline’s per-passenger profit margin could suffer.

Allegiant’s strategy appears to be one of "wait and see." By observing how competitors interact with these AI platforms, the airline is attempting to gauge whether the increase in booking volume justifies the loss of direct customer data and the erosion of ancillary sales opportunities.
Supporting Data: The Cost of Customer Acquisition
The challenge faced by Allegiant is reflected across the broader aviation sector. According to reports from the International Air Transport Association (IATA), customer acquisition costs (CAC) for airlines have increased by approximately 15% over the past three years. This is driven by the rising cost of digital advertising on platforms like Meta and Google, as well as the increasing fragmentation of the travel booking funnel.
For an airline like Allegiant, which operates on razor-thin margins, these costs are significant. If a traveler discovers a flight on a third-party site but completes the purchase on the airline’s website, the airline still pays for the initial "touchpoint." By integrating more deeply with OTAs, Allegiant is essentially buying into a more expensive but potentially more reliable acquisition funnel, trading short-term margin for long-term market share.
Industry Implications and Future Outlook
The broader impact of these trends suggests a future where the "airline website" becomes just one of many touchpoints rather than the sole destination for travelers. Industry analysts suggest that we are moving toward a "distributed retailing" model, where airlines must be able to push their entire product catalog—including fares, ancillaries, and loyalty benefits—to any digital endpoint, whether that is a social media app, a virtual assistant, or a travel-specific AI agent.
For Allegiant, the path forward requires a delicate balancing act. They must modernize their IT infrastructure to support the APIs (Application Programming Interfaces) necessary for these complex third-party integrations, all while maintaining the lean, cost-focused culture that has made them a success.
"We are constantly evaluating the trade-offs," Wells noted during the session. The implication is clear: the airline is not opposed to technology, but it is deeply committed to protecting its specific value proposition. Allegiant’s business model relies on serving price-sensitive customers who are often traveling for leisure, visiting friends, or vacationing in specific, non-hub cities. If the AI platforms that these customers use cannot accurately communicate the unique value of the Allegiant experience, the airline will continue to prioritize its own direct channels.
Conclusion: The Strategic Road Ahead
As the aviation industry approaches the next decade, the ability to control the "digital storefront" will likely be the primary differentiator between successful airlines and those that struggle to maintain their bottom line. Allegiant’s approach, as described at the Skift Aviation Forum, serves as a case study in measured digital evolution.
By cautiously experimenting with partnerships like Expedia while maintaining a disciplined focus on their direct-to-consumer core, Allegiant is attempting to future-proof its business without succumbing to the "hype cycle" of AI integration. The outcome of this strategy will be closely watched by the industry, as other carriers, both large and small, face similar pressures to modernize their distribution strategies in an era of unprecedented technological disruption. Whether the future of travel booking will be dominated by massive, AI-powered aggregators or whether niche carriers can continue to carve out their own digital territory remains one of the most pressing questions in modern aviation management.