Beyond the Pipeline: Why Hotel Ownership Experience Defines the Future of Asset-Light Growth

In the high-stakes world of global hospitality development, the industry has long relied on a singular, quantifiable metric to measure success: net unit growth. For decades, hotel groups have touted the number of properties signed, the thousands of rooms added to the development pipeline, and the expansion of their geographic footprint as the ultimate scorecard of health. Yet, as global macroeconomic conditions shift, a critical disconnect has emerged between the growth goals of operators and the financial realities faced by property owners. While unit counts are easily tracked, they fail to reveal the most vital information for an investor: the return on capital, the efficiency of EBITDA conversion, and the long-term appreciation of the asset.
Wayne Williams, Chief Financial Officer of Minor Hotels, argues that the industry is at a pivotal crossroads. For an asset-light operator, net unit growth is an entirely logical measure of scale, representing how efficiently the system is expanding and how future fee streams are being generated. However, Williams warns that owners must not confuse operator-centric metrics with owner-centric ones. In an environment defined by high interest rates, elevated construction costs, and persistent project delays, the cost of an incorrect development decision has never been higher. Consequently, the quality of growth—measured by the durability of cash flow and the precision of capital deployment—has become significantly more important than the pace of expansion.
The Evolution of the Asset-Light Model
The shift toward asset-light business models has been the dominant trend in the hospitality sector for the past two decades. By offloading the ownership of real estate, major hotel brands have been able to scale their distribution, loyalty platforms, and marketing reach with unprecedented speed. This transition allowed operators to mitigate the risks associated with property ownership, such as maintenance liabilities and fluctuating real estate values, while focusing on brand equity and service standards.
However, the transition to an asset-light model does not mean the underlying hotel has become light. The physical constraints of real estate, the necessity for constant capital expenditure (CapEx), and the operational complexities of labor and energy costs remain as heavy as ever. The fundamental change lies in the allocation of risk. When an operator manages a property they do not own, they are acting as a steward of someone else’s capital. This creates an essential alignment test: when an operator proposes a multimillion-dollar renovation, a shift in restaurant concept, or a technology upgrade, would they make the same recommendation if the capital being deployed were their own?
Minor Hotels occupies a unique position in this landscape. While the company is aggressively expanding its pipeline through asset-light deals—with more than 85% of its current development pipeline being asset-light, up from approximately 70% just a year ago—roughly 70% of its existing portfolio remains owned or leased. This dual identity serves as an internal check-and-balance system. Because Minor Hotels maintains significant capital exposure, the firm’s financial leaders experience the same financing costs, labor shortages, and energy price volatility that plague its third-party owners.
Strategic Capital Allocation and the 2023-2024 Performance Shift
The practical application of this "owner-first" philosophy was evidenced in the performance of the Minor Hotels European portfolio during the 2023 and 2024 fiscal periods. During this time, the company identified 43 properties within its existing footprint that required strategic intervention. Rather than pursuing new, flashy developments to pad the pipeline, the leadership team committed more than $110 million to the renovation and repositioning of these specific assets.
The results were statistically significant. By focusing on existing assets rather than new builds, the company saw EBITDA across these 43 properties increase by approximately 40% by 2025. In contrast, comparable hotels within the broader market segment saw EBITDA growth of roughly 14% over the same timeframe. This performance gap highlights the difference between growth for the sake of unit count and growth for the sake of value creation. For Minor Hotels, the objective was not to increase the number of rooms in the portfolio, but to increase the earnings potential of the square footage already under management.
This approach reflects a rigorous methodology for capital allocation. Every project is scrutinized not just at the point of signing, but throughout its lifecycle. If the macroeconomic environment shifts—whether through interest rate hikes or a change in the competitive landscape—the company remains prepared to adjust the scope, phase the investment, or even halt the project entirely. This active management style is a byproduct of having "skin in the game," ensuring that the feedback loop between capital expenditure and financial performance remains immediate and transparent.
Testing Concepts Before Scaling
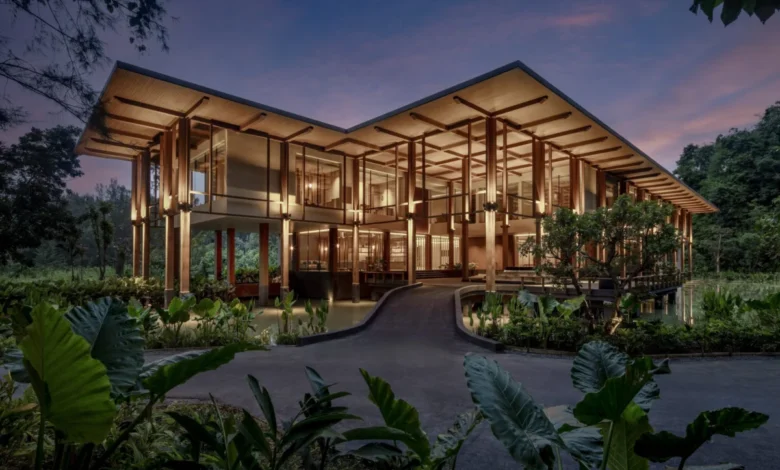
The benefits of maintaining an owned portfolio extend beyond simple asset management; they serve as a critical incubator for innovation. Before rolling out new concepts to third-party owners, Minor Hotels utilizes its own properties as testing grounds. A prime example of this is the Layan Life facility in Phuket, a purpose-built medical wellness and longevity center.
By investing over $11 million into the Layan Life property, Minor Hotels was able to navigate the early-stage risks of a nascent concept—assessing customer demand, refining the marketing model, and optimizing the operational economics—without subjecting third-party partners to those risks. This "proof-of-concept" phase is a key differentiator in an industry where operators often push new programs onto owners prematurely. By the time a concept is introduced to the wider network, the bugs have been ironed out, and the data-driven business case is established.
This internal testing strategy applies not just to physical guest experiences, but to the operational backbone of the company. Before deploying new cloud-based financial systems or advanced automation tools, the company tests them within its owned hotels. This ensures that when a new technology is rolled out to the broader system, the operator can provide proven, actionable insights on how that technology drives productivity and cost management.
The Changing Questions for Hotel Owners
As the hospitality industry continues to favor asset-light expansion, the power dynamic between operators and owners is shifting. While brand reach, loyalty program depth, and global distribution systems remain essential pillars of the partnership, they are no longer sufficient to justify a management contract. Owners are increasingly demanding greater transparency and evidence of an operator’s ability to protect the asset’s value during periods of volatility.
Industry experts suggest that owners should move beyond asking about the size of an operator’s pipeline. Instead, the focus must turn to the "alignment of incentives." When vetting a potential operator, owners should pose fundamental questions:
- What is the operator’s track record in converting gross revenue into bottom-line EBITDA?
- How does the operator’s management team respond to cost inflation in real-time?
- What is the operator’s history of managing capital expenditure cycles to ensure maximum return on investment?
- Most importantly, if this were the operator’s own capital, would they be making this specific recommendation?
This shift in questioning is vital. The industry’s obsession with pipeline statistics often obscures the granular reality of hotel management. An operator that views a property merely as a "flag" in a global system is fundamentally different from an operator that views each hotel as an individual business entity. The latter approach requires an understanding of local market dynamics, source market shifts, and the subtle interplay between service quality and operational costs.
Implications for the Future of Development
The debate over the best development model is not a binary choice between ownership and asset-light expansion. Rather, the future of the industry lies in the synthesis of the two. Operators that maintain a degree of capital exposure—or at least a culture that mimics the mindset of an owner—are better positioned to navigate the challenges of the coming decade.
The current economic climate, characterized by higher costs of capital and increased operational friction, acts as a filter. It rewards operators who can prove that their systems, brands, and management techniques translate into tangible value for the owner. As the industry moves forward, the most successful operators will likely be those who can scale their reach while maintaining the agility and disciplined financial oversight typically found in owner-operators.
Ultimately, the growth of a brand’s footprint is a vanity metric if it comes at the expense of the individual asset’s health. Owners who prioritize partners with a proven, data-backed approach to capital management will be better equipped to withstand the cyclical nature of the travel industry. The lesson for the modern hotel investor is clear: look past the press releases detailing new property signings and look toward the operational philosophy that guides the decisions made long after the contract is signed. The true measure of an operator’s worth is not found in the size of its pipeline, but in the enduring value of the assets it stewards.