UAE Hospitality Sector Pivots Toward Short-Haul Markets Amid Global Geopolitical Instability and Rising Travel Costs

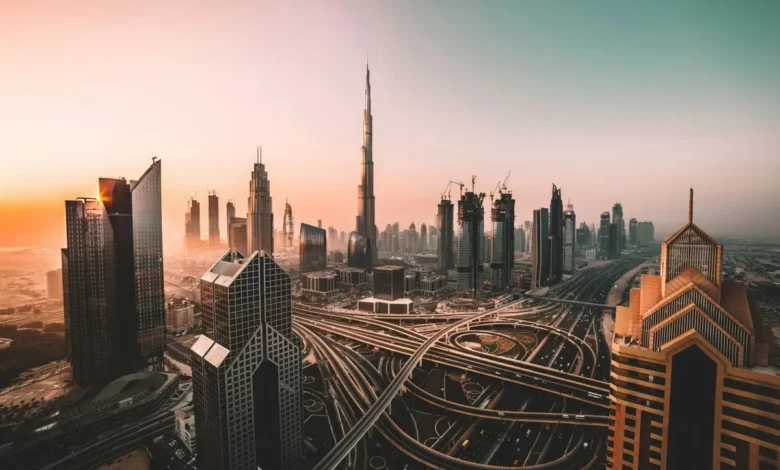
The hospitality landscape in the United Arab Emirates is undergoing a strategic recalibration as industry leaders navigate the dual headwinds of regional geopolitical volatility and persistent inflationary pressures in the aviation sector. As the lingering echoes of the U.S.-Iran tensions continue to influence global perception of Middle Eastern travel, major hotel operators are shifting their focus away from traditional long-haul markets—specifically the Americas and Australia—to concentrate on high-growth, short-haul corridors. By prioritizing visitors from India, China, and Russia, UAE-based hoteliers are implementing a defensive growth strategy designed to maintain occupancy rates and revenue stability in an era defined by exorbitant jet fuel prices and cautious consumer sentiment.
The Strategic Shift: Redefining the Source Market Mix
For decades, the UAE—and Dubai in particular—functioned as a global crossroads, attracting a balanced mix of travelers from Europe, North America, and Asia. However, the current economic climate has rendered the long-haul traveler a luxury that the market can no longer exclusively rely upon. Saurabh Tiwari, Vice President for the Middle East, Maldives, and Sri Lanka at IHCL, the parent company of the prestigious Taj hotel brand, has been vocal about this necessity.
“We are targeting short-haul markets like India, China, and Russia, which are a five- to six-hour flight away,” Tiwari stated, highlighting the geographic limitations imposed by modern economic realities. “Since jet fuel prices are significantly higher than they were in previous cycles, it is difficult to expect consistent demand from long-haul markets like the Americas or Australia. Attempting to drive volume from those regions at this juncture is, frankly, wishful thinking.”
This pivot is not merely a preference but a survival mechanism. Long-haul flights have seen ticket prices soar as airlines pass the costs of volatile oil markets and increased operational expenses onto the consumer. For the average leisure traveler, the price sensitivity threshold has lowered, making the shorter, more affordable transit routes from the Indian subcontinent and the Commonwealth of Independent States (CIS) the most viable engines for the UAE’s tourism recovery.
Chronology of a Shifting Landscape
To understand the current state of the UAE hospitality market, one must look at the timeline of events that have shaped the current environment.
- 2019–2020: The UAE hospitality sector faced initial disruptions as regional tensions began to simmer, leading to a temporary plateau in arrivals from Western markets.
- 2021–2022: The post-pandemic rebound saw a massive surge in "revenge travel," with high demand from both long-haul and short-haul visitors. However, the subsequent rise in energy prices, exacerbated by global geopolitical conflicts, began to compress disposable income for long-distance travelers.
- 2023–2024: The escalation of regional geopolitical tensions, specifically concerning the U.S.-Iran dynamic, led to a renewed, albeit localized, caution among travelers from Western nations. Simultaneously, the sustained high cost of jet fuel finalized the shift in strategy for hotel operators, who began to double down on the "five-to-six-hour flight radius."
Data-Driven Realities: The Rise of India and the CIS
The data supports the industry’s pivot. India has emerged as a powerhouse for the UAE tourism sector. Proximity, coupled with increasing disposable income among India’s middle and upper-middle classes, has made the country the most reliable source of guests for major hotel groups. IHCL, among others, has reported that its Indian clientele is not only offsetting the decline in Western visitors but is also showing a propensity for longer stays and higher average spending on auxiliary services like fine dining and spa treatments.
Furthermore, the influx of visitors from the Russian Federation and CIS countries has provided a critical buffer. Following recent geopolitical shifts, Dubai has become a primary hub for Russian capital and tourism, with direct flight connectivity remaining robust. This demographic is characterized by a demand for luxury, high-end retail, and premium hospitality services, which aligns perfectly with the UAE’s existing inventory of five-star and ultra-luxury properties.
The Economic Implications of Operational Costs
The central issue remains the cost of air travel. Aviation turbine fuel (ATF) prices remain a volatile component of the global travel ecosystem. For a family of four traveling from New York or Sydney, the airfare component of a vacation to Dubai now represents a substantially larger percentage of the total budget compared to pre-2020 levels.
Economists point out that this is not a temporary fluctuation but a structural change in the travel industry. As airlines move toward sustainable aviation fuel (SAF) mandates and face aging fleet maintenance costs, the "cheap long-haul" era appears to be in a state of indefinite suspension. For the UAE, this means the competitive advantage must shift from "global accessibility" to "regional destination appeal."
Official Responses and Market Adaptations
While hotel operators are vocal about the challenges, the UAE government and tourism boards have been proactive. Initiatives such as the "Dubai Sustainable Tourism" program and the expansion of visa-on-arrival policies for key markets like India and China are deliberate efforts to lower the barrier to entry.
Industry analysts suggest that the UAE’s hotel inventory is also evolving. There is a noticeable shift in the development pipeline toward mid-market and upscale properties that cater to the price-conscious but experience-driven traveler from emerging economies. This move away from an "ultra-luxury only" narrative is seen as a necessary evolution to maintain high occupancy rates throughout the year, especially during the shoulder seasons.
The Impact on Hospitality Services
The shift in source markets has necessitated a change in how hotels operate. Staffing is increasingly focused on language capabilities—Hindi, Russian, and Mandarin are now as critical as English and Arabic in many hotel lobbies. Culinary offerings are also being recalibrated to suit the preferences of these dominant source markets, with hotels introducing more diverse menus that cater to the specific dietary and cultural expectations of guests from the Indian subcontinent and East Asia.
Furthermore, marketing budgets are being reallocated. Traditional advertising campaigns in London, New York, and Sydney are being scaled back in favor of aggressive digital marketing and influencer partnerships in Mumbai, Delhi, Shanghai, and Moscow. This shift is expected to yield higher conversion rates, as the target audience is already within a feasible geographic range to act on travel deals.
Looking Toward the Future: Resilience and Adaptation
The long-term outlook for the UAE hospitality sector remains positive, provided it continues to demonstrate this agility. The transition from a "global magnet" to a "regional hub of choice" is a sign of a maturing market. By anchoring its growth in the robust, high-population markets of Asia and the CIS, the UAE is insulating itself against the volatility of Western economic cycles and the geopolitical sensitivities that have historically hampered long-haul travel.
The analysis remains clear: while the absence of a broad, global traveler base may feel like a contraction, the reality is a consolidation of the market. The UAE has successfully identified where the growth is, and by aligning its operational and marketing strategies with these regions, the sector is ensuring that its skyline remains a destination of choice, regardless of the challenges posed by the global geopolitical climate. As the industry moves forward, the success of the Taj brand and its peers will serve as a bellwether for the rest of the hospitality sector in the region, proving that in the face of macro-economic uncertainty, proximity is the new currency of success.