A Recalibration of Ambition
The Thai government, through the Tourism Authority of Thailand (TAT) and the Ministry of Tourism and Sports, recently downwardly adjusted its future arrival forecasts. The revised figures indicate a target of 33 million international arrivals for 2026, a notable retreat from the previous estimate of 36.7 million. Looking ahead to 2027, the government has set a baseline goal of “at least 33 million,” signaling that the growth trajectory has entered a period of stabilization rather than the exponential recovery originally anticipated following the lifting of global travel restrictions.
This reduction in targets reflects a complex reality. While Thailand’s tourism sector is undeniably resilient, it is contending with a shifting global macroeconomic climate. Inflationary pressures, reduced disposable income in key source markets—such as Europe and parts of North America—and a slower-than-expected resurgence in Chinese outbound travel have all contributed to the conservative outlook. The government’s move to lower its expectations serves as both a pragmatic acknowledgment of current headwinds and a tool to manage the expectations of stakeholders who had banked on a rapid return to pre-2019 volumes, which peaked at nearly 40 million visitors.
The Chronology of Recovery and Reset
To understand the current sentiment, one must look back at the trajectory of Thailand’s tourism recovery.
- 2019 (Pre-Pandemic Baseline): Thailand recorded a record-breaking 39.9 million international visitors, cementing its status as a global tourism powerhouse.
- 2020–2021 (The Shutdown): International travel to Thailand effectively ceased, leading to a near-total collapse of the tourism-dependent economy.
- Late 2022 (The Reopening): Thailand began a phased reopening, starting with the “Phuket Sandbox” initiative, which gradually evolved into full-scale border openings.
- 2023 (The Initial Rebound): The year was defined by a surge in "revenge travel." While the numbers were strong, they failed to hit the most optimistic government targets, leading to early discussions about the sustainability of the recovery.
- 2024 (The Current Adjustment): The government has begun to refine its data models, moving away from purely volume-based targets toward a model that emphasizes high-value tourism. The lowering of the 2026 and 2027 targets is the latest chapter in this shift toward quality over quantity.
The Private Sector Paradox: Continued Expansion
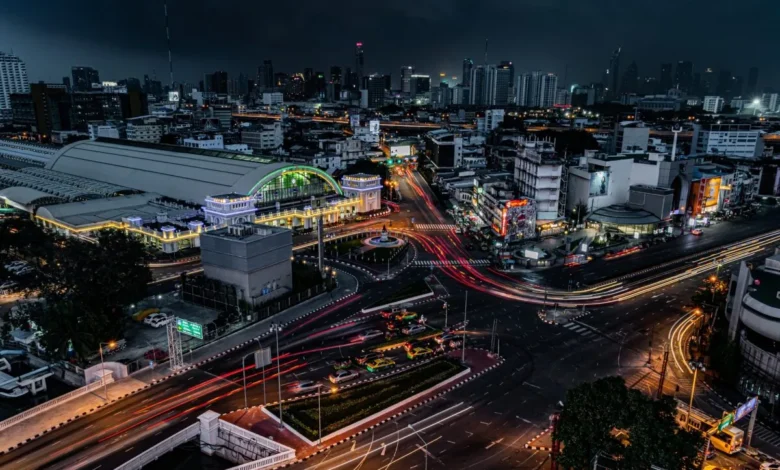
Despite the government’s tempered enthusiasm, hotel developers and airline operators continue to pour capital into the Thai market. In major urban centers and emerging tourism hubs, construction cranes remain a permanent fixture of the skyline.
This expansion is driven by a long-term belief in Thailand’s fundamentals. Developers argue that even if total arrival numbers fall short of initial forecasts, the composition of those arrivals is changing. There is a distinct, measurable trend toward luxury and high-end travel. Bangkok’s luxury hotel sector, for instance, has demonstrated remarkable resilience. High-net-worth individuals continue to visit the capital, keeping occupancy rates and average daily rates (ADR) in the premium segment significantly higher than in the budget or mid-market tiers.
However, the expansion is not uniform. Phuket is currently navigating a significant wave of new inventory. With thousands of new rooms slated to come online through 2026, analysts are voicing concerns regarding potential oversupply. If the arrival numbers do not materialize as hoped, the resulting price competition could erode the profitability of existing operators, creating a "race to the bottom" in terms of room rates that could threaten the viability of smaller, independent properties.
Supporting Data and Market Dynamics
Data from the Ministry of Tourism and Sports indicates that while total arrivals are growing, the average length of stay and the per-capita expenditure have fluctuated. In 2023, the average visitor spent roughly 45,000 to 50,000 THB per trip. The government’s pivot to "quality tourism" seeks to increase this figure, aiming for high-spending demographics rather than mass-market tour groups.
Airlines have similarly bet on capacity. Increased flight frequencies from Middle Eastern hubs and the gradual return of direct flights from secondary Chinese cities suggest that aviation stakeholders believe the bottleneck for tourism is not a lack of interest, but rather the logistical capacity to move passengers. Yet, the mismatch between the number of seats offered and the actual passenger load factors serves as a reminder that demand must be stimulated, not just assumed.
Official Responses and Industry Sentiment
While the Ministry of Tourism and Sports has remained publicly optimistic about the long-term potential of the sector, the lowering of the 2026/2027 targets has sent a clear message to the industry: the era of "easy growth" is over.
Industry analysts suggest that the government is trying to prevent the kind of over-tourism that led to the degradation of natural assets in previous years. By setting more realistic targets, the authorities have more flexibility to focus on infrastructure, environmental sustainability, and the promotion of secondary destinations.
From the perspective of hotel chains, the reaction has been a pivot to "brand diversification." Many major international hotel brands are focusing on boutique and lifestyle segments, which appeal to the younger, more discerning traveler who is less sensitive to global economic fluctuations. These operators are betting that Thailand’s cultural and culinary appeal remains a "must-have" experience, regardless of whether the headline arrival numbers hit 33 million or 36 million.
Broader Implications and Future Outlook
The implications of this supply-demand gap are significant. For the Thai economy, tourism accounts for roughly 12% to 18% of GDP depending on how indirect contributions are calculated. A shortfall in arrival numbers—even if mitigated by higher spending—places pressure on the national budget and current account balance.
Moreover, the disparity between the luxury sector’s performance and the saturation of the mid-market in regions like Phuket highlights a structural challenge. The industry must navigate a transition where growth is no longer a given. Stakeholders will need to focus on:
- Market Diversification: Reducing over-reliance on a few key markets, such as China, by incentivizing travel from India, the Middle East, and Southeast Asian neighbors.
- Infrastructure Upgrades: Ensuring that the physical infrastructure—from airport capacity to urban transport—can support the quality of experience expected by high-spending travelers.
- Sustainability: Addressing the environmental costs of mass tourism, which has historically been a point of contention in Thailand’s coastal provinces.
The coming three years will be a litmus test for Thailand’s tourism strategy. If the government’s new, lower targets are met with a more disciplined approach to supply—meaning slower, more intentional expansion—the industry may emerge more profitable and sustainable. Conversely, if the private sector continues to aggressively increase capacity in the face of stagnant arrival growth, the industry risks entering a cycle of intense price competition and declining service quality.
Ultimately, Thailand remains a premier global destination. The adjustment of the 2026 and 2027 forecasts is not an indictment of the country’s appeal, but rather a maturity of its tourism policy. By aligning public targets with private sector investment, Thailand is attempting to chart a path toward a more stable and resilient future. The challenge, however, remains in the execution: can the nation entice the travelers it wants, while managing the massive infrastructure it has already built? Only time, and the arrival data of the next few years, will provide the answer.
Related posts: